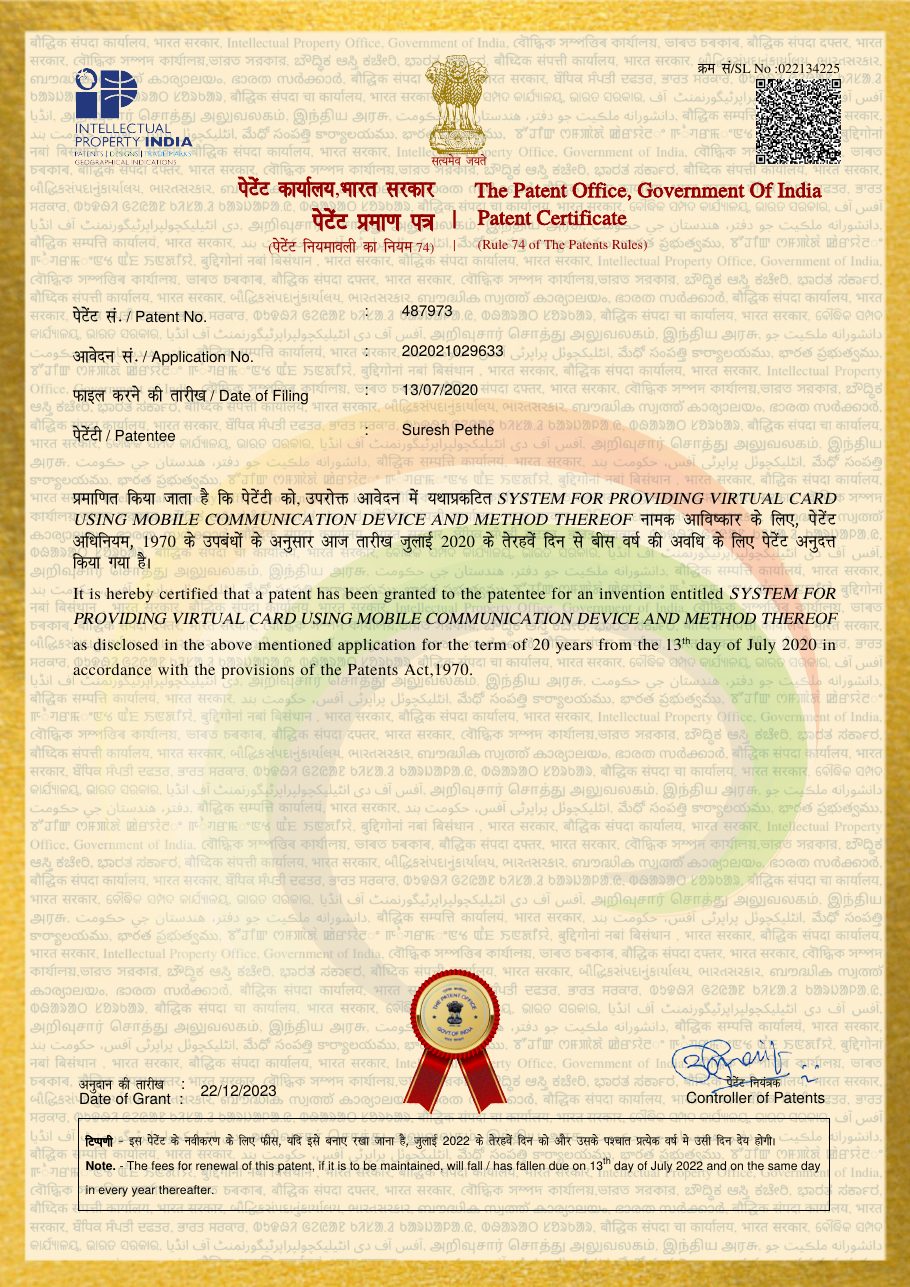
- Application
- 202021029633
- Filed
- 13 Jul 2020
- Granted
- 22 Dec 2023
- Authority
- The Patent Office, Govt. of India
For over 50 years, consumer credit has followed one principle: provide credit first, earn revenue later through utilisation and interest. PECAPS asks a different question: what if a bank could generate revenue when credit is activated, while keeping complete control of the customer, the credit, the risk and the economics? PECAPS turns a bank's existing sanctioned OD/CC line into an event-driven push rail: credit is activated at checkout and the merchant is settled instantly over IMPS.
From Sanctioned Limit to Purchasing Power. Zero MDR for Merchant. Instant Credit for Customer. Higher Yield for Bank.
The patented architecture behind PECAPS changes the direction of credit: it is delivered to the point of payment when a purchase happens, under the bank's own control.
PECAPS is the flagship product built on this patented architecture, delivering the push-type credit rail to banks.
Same bank, same customer, same sanctioned line. What changes is when credit is activated, and how the merchant is paid.
The question for every bank: can a profitable credit business be built without growing dependence on revolving-credit interest?
PECAPS (Purchase Enabled Credit Activation & Payment Settlement) sits under the bank's own credit business. It does not replace the bank, compete with it, or take its customer.
PECAPS shifts credit delivery from a pre-funded or pull-based mechanism to an event-driven push rail. Here is how it differs from the rails in use today.
| Credit cards (Visa / Mastercard) | Merchant BNPL / FinTech loans | Traditional overdraft / cash credit | PECAPS framework | |
|---|---|---|---|---|
| Credit source | Unsecured revolving card line | New micro-loan origination per checkout | Sanctioned line against collateral / turnover | Existing sanctioned OD/CC line in CBS |
| Activation point | Always active / card balance | At point of sale (requires underwriting API) | Pre-drawn or manual net-banking transfer | At checkout; zero pre-draw idle cost |
| Rail type | Card scheme pull rail | Proprietary aggregator API | NEFT / RTGS / manual transfer | Push rail over instant clearing (IMPS) |
| Merchant cost (MDR) | 1.5% – 3.0% interchange + gateway fees | 2.0% – 4.0% merchant subvention | Zero (standard direct bank transfer) | Low-cost account-to-account (A2A) rail |
| Settlement time | T+1 to T+2 days | T+1 to T+3 days | T+0 (if manual RTGS / IMPS) | Instantaneous (real-time gross settlement) |
| Capital & underwriting risk | Card-issuing bank / NBFC | BNPL NBFC / FinTech partner | Lending bank | Remains 100% with the sanctioning bank |
No third party is involved; data security and sovereignty are at the highest level and per regulatory compliance.
One checkout event serves the lending bank, the merchant and the borrower.
Zero MDR for Merchant. Instant Credit for Customer. Higher Yield for Bank.
Seven things that stay with the bank, with no exceptions.
The customer remains the bank's customer.
The credit remains the bank's credit.
The economics remain the bank's economics.
Every transaction is traceable as it is processed in CBS.
Works with the payment ecosystems your customers already use.
PECAPS settles over instant clearing (IMPS) and is compatible with existing payment ecosystems, so adopting it does not mean asking customers, merchants or networks to change.
PECAPS offers a framework for exploring that opportunity.
Start the conversationInventor and patentee: Suresh Pethe, Pune. Protected for 20 years from the filing date.


Title of the invention: System for providing virtual card using mobile communication device and method thereof.
Write to us with your institution's name and what you'd like to explore. We'll reply by email.
Papers, articles and notes on PECAPS and bank-controlled credit activation.